Home insurance pack · updated 2026
Home insurance in France: the tenant, landlord and holiday-home pack
Who it is for: English speakers who rent a home in France and also own, or are buying, a flat or a house there
- 6chapters
- 8checklist items
- 11tables
- 19links to the official texts
- 3kits included
Checked before every release
- 51automated testsrun at every release: prices, links, pages and content checked before publication.
- 19links to the textsthe main official sources cited in the kit (Légifrance, Service-public…), for you to check.
- 18 November 2026last updatelatest update of the kits; you always read the latest version.
Built from the texts and data of Légifrance, Service-public.fr, La Médiation de l’assurance, Visale.
€49VAT included · one payment · instant access
Get the pack — €49 Read chapter 1 free
6 chapters online (a 4-question route by role, who must insure what side by side, 4 households with several homes, one calendar for all your homes, and the 3 home kits included). €49, VAT included, one payment, instant access, printable to PDF, invoice by email. The 3 kits inside cost €72 bought separately: the guide comes on top.
As described, or refunded · updates included, at no cost · terms of sale
Secure payment by Stripe · card, Apple Pay, Google Pay · Instant access, no subscription
After payment
- Instant access to the complete kit on its access page, to bookmark or print to PDF.
- Your Stripe invoice is sent to the email address you paid with.
- Your links at any time: Find my purchases emails you a link valid for 24 hours.
- A week later, one email asks for your review, only once.
- No calls, no text messages: buying does not pass your details to brokers. Only the broker request form does, with your consent.
What you get
- The pack guide: 6 chapters (a 4-question route by role, who must insure what side by side, 4 households with several homes, one calendar for all your homes, and the 3 home kits included)
- Included: 8 checklist items, 11 tables
Find out in four questions which rules apply to you, as a tenant, as a landlord, as the owner of a holiday home or in several of these roles at once, see who must insure what, follow one yearly calendar for all your homes, and go straight to the right chapter of the three home kits included.
Who it is for
- English speakers who rent a home in France and also own, or are buying, a flat or a house there
- Owners who let a French flat or house, from France or from abroad, and want the tenant’s duties and their own side in one place
- Owners of a holiday home in France who live elsewhere, lend it to family or let it a few weeks a year
- Anyone whose situation is changing: moving abroad and letting the former main home, letting a holiday home on a lease, a student child renting in France
Contents of the complete pack
- Which role is yours? Four questions, one route (free extract below)
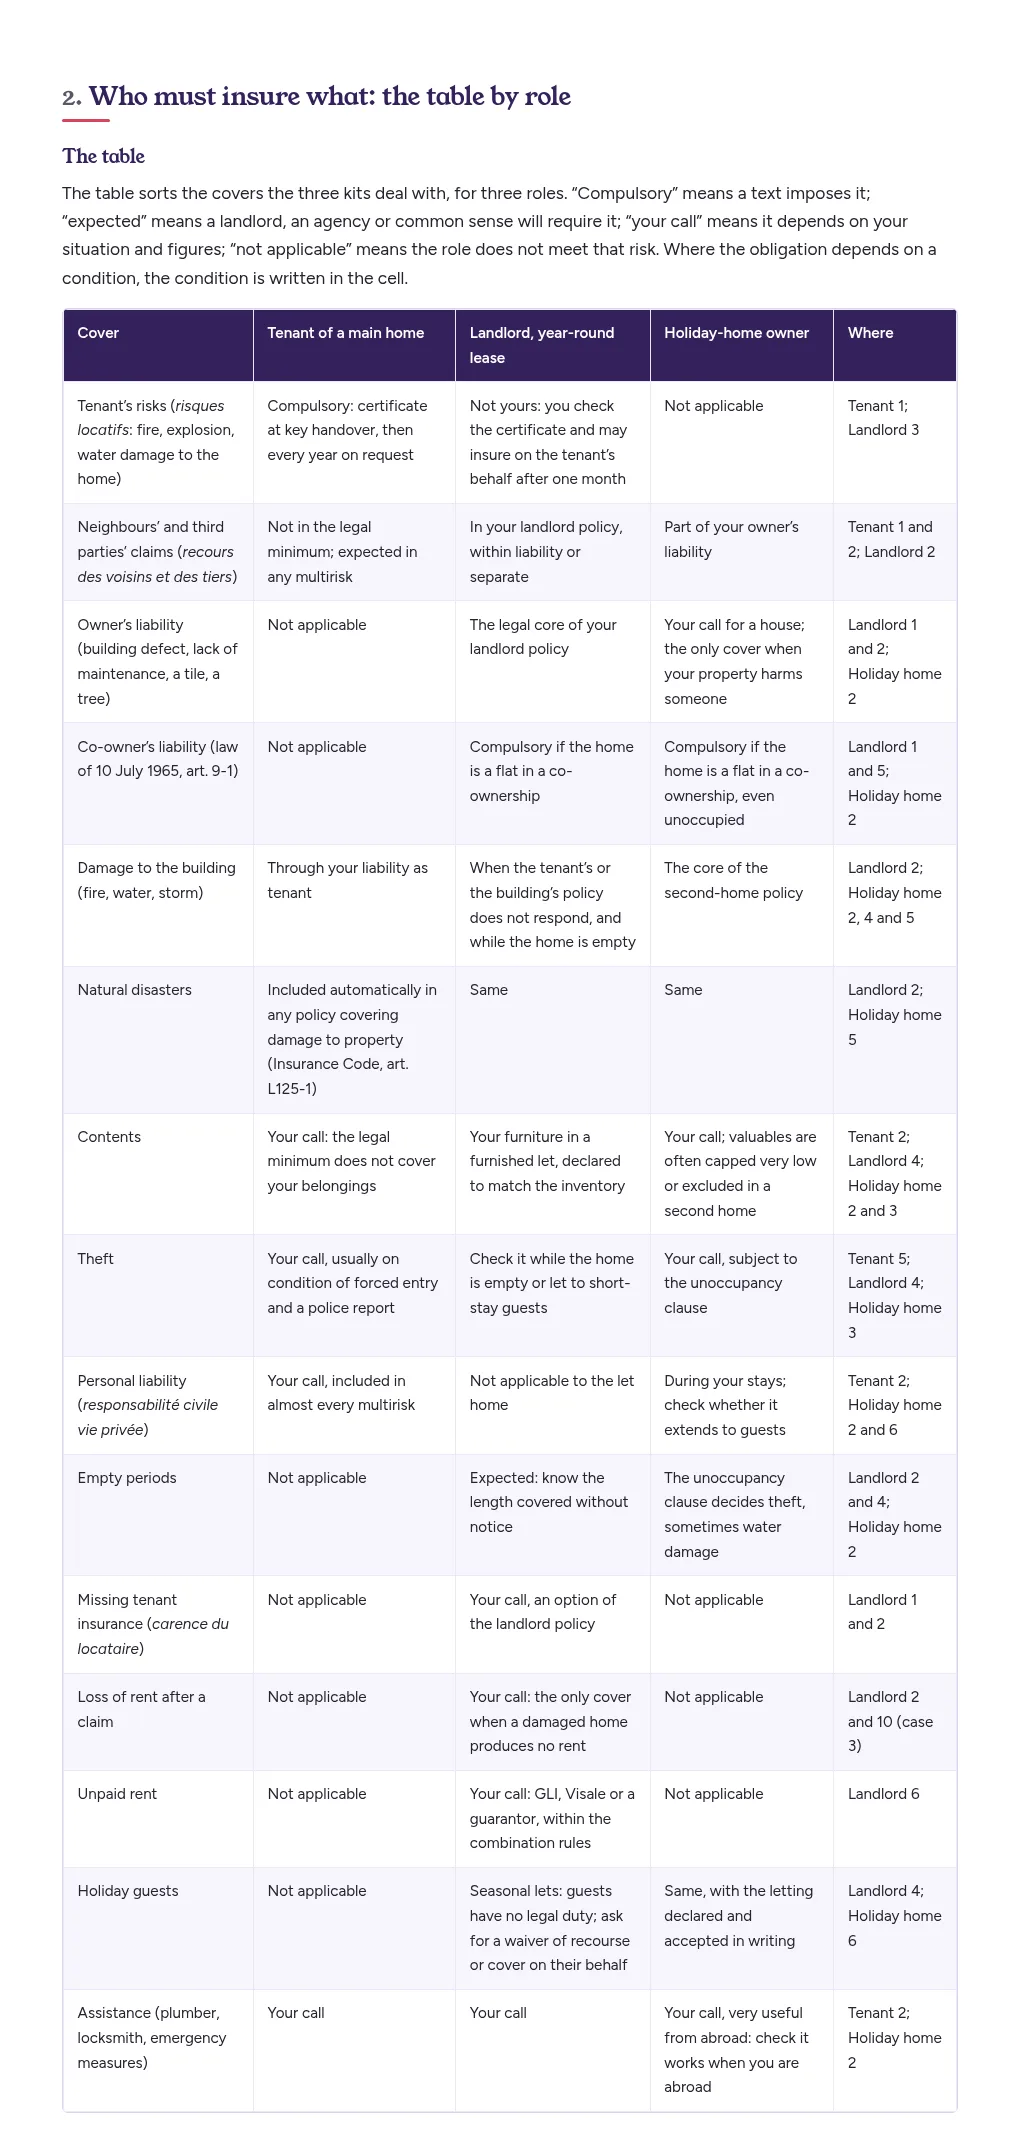
- Who must insure what: the table by role
- Several roles, one person: four households and the three kits
- One calendar for all your homes
- The three kits, chapter by chapter, and the index
- When something happens: who handles it, and the right letter
What you get
- The complete guide: 6 chapters, about 6000 words (8 checklist items, 11 tables)
- Included: Renting in France: the tenant insurance kit, in English and in French (9 chapters)
- Included: Landlord insurance in France: the property owner’s kit, in English and in French (12 chapters)
- Included: Holiday home in France: the insurance kit for owners who live elsewhere, in English and in French (10 chapters)
The 3 included kits are sold separately: €72 in total.
Introduction
In France, home insurance is not one policy per house but one per role. The tenant who lives in a home must insure it against fire, explosion and water damage, and prove it to the landlord. The landlord answers for the building and for the gaps the tenant’s policy leaves, and in a block of flats every co-owner must hold liability insurance, whether they live there or not. The owner of a holiday home insures a house that stands empty most of the year, under clauses that reduce cover after a number of days without occupants. Many English speakers in France hold two of these roles at once, sometimes three, and the mistakes happen at the joins: a policy kept after the use of the home changed, a claim reported to the wrong insurer, a deadline missed because the letter went to an empty letterbox.
This pack brings together our three home kits: the tenant kit (the legal duty, the right policy, students, flat-shares and furnished lets, water damage, moving out), the landlord kit (the landlord policy, called PNO, the tenant’s certificate and what to do without it, unpaid rent, co-ownership rules, letting from abroad) and the holiday-home kit (unoccupancy clauses, frost, theft, storms and natural disasters, occasional letting, claims from abroad). The guide that comes with them does not repeat their content: it points you to it. Chapter 1 asks four questions and sends you to the right chapter of the right kit. Chapter 2 sets out who must insure what, role by role. Chapter 3 follows four households with several roles through the three kits, with figures. Chapter 4 is one yearly calendar for all your homes. Chapter 5 gives the contents of the three kits and an index by topic, and chapter 6 the common path when something happens, with the letter to send at each step.
How to read it: start with chapter 1, answer for each home you hold, then open the chapter indicated. After purchase, the links to the three kits are at the bottom of the pack’s page. Chapter numbers refer to the numbered contents of each kit.
Which role is yours? Four questions, one route
Answer the questions in order, once for each home you hold, and stop at the first one that matches that home. Each answer gives the essential rule, then the chapters to open. The three kits are called here Tenant (the tenant kit, 9 chapters), Landlord (the landlord kit, 12 chapters) and Holiday home (the holiday-home kit, 10 chapters).
One rule sits above the four questions. In France, home insurance follows the use of the home, not ownership alone: who lives there, on what kind of lease, for how much of the year, and whether the home is a flat in a co-ownership building (copropriété). The same flat can need a tenant’s policy and a landlord policy at the same time, and a policy written for a home you live in does not automatically fit once you let it (Tenant 1; Landlord 1; Holiday home 2).
Question 1: do you rent the home you live in?
Article 7 g of the law of 6 July 1989 requires the tenant of a main home, unfurnished or furnished, including the short bail mobilité, to insure the risques locatifs: fire, explosion and water damage to the rented home. The certificate (attestation d’assurance) is handed over when you receive the keys, then every year if the landlord asks. The legal minimum does not cover your belongings, the neighbour below or your personal liability, which is why almost every tenant takes a multirisque habitation instead. If the landlord does not receive the certificate, he chooses one of two routes, each starting with one month for you to act: the termination clause of the lease, or insurance taken out on your behalf, recovered with the rent plus at most 10 %.
| Your question | Kit | Chapter |
|---|---|---|
| What the law requires, and what the minimum leaves out | Tenant | 1 |
| The landlord asks for the certificate, or announces he will insure for you | Tenant | 1 and 7 (case 3), letters 1 and 5 of chapter 8 |
| Comparing policies: the 14-point grid and three typical levels | Tenant | 2 |
| I am a student, or the parent of a student renting in France | Tenant | 3, letter 2 |
| Flat-share, furnished let, bail mobilité | Tenant | 4, letters 3 and 4 |
| Water through the ceiling, a burglary | Tenant | 5, letter 6 |
| A claim refused | Tenant | 5, letter 8 |
| Moving, switching insurer, leaving France | Tenant | 6, letter 7 |
Question 2: do you let a home you own to a tenant?
The tenant insures the risques locatifs; your landlord policy (propriétaire non occupant, PNO) covers your liability as owner and the gaps: the home empty between two tenants, damage coming from the building itself, a tenant who is not insured. If the home is a flat in a co-ownership building, insuring your liability as a co-owner is compulsory (law of 10 July 1965, art. 9-1). For a house you let, no text obliges you to insure, but only your own policy responds when the tenant’s does not. Holidaymakers in a seasonal let have no legal duty to insure your home: the 1989 law does not apply to seasonal lets (art. 2).
| Your question | Kit | Chapter |
|---|---|---|
| Who insures what in a let home | Landlord | 1 |
| Choosing or checking a landlord policy: the 12-point grid | Landlord | 2 |
| The tenant’s certificate is missing: the two procedures, the sum you can recover | Landlord | 3, letters 1, 2 and 3 of chapter 11 |
| Furnished let, flat-share, holiday let, empty period or works | Landlord | 4, letter 8 |
| A flat in a co-ownership: the building policy, the managing agent, water damage between flats | Landlord | 5, letters 7 and 9 |
| Unpaid-rent insurance (GLI), the Visale guarantee or a personal guarantor | Landlord | 6 |
| A rent payment is late | Landlord | 7, letters 5 and 6 |
| A claim in the let home | Landlord | 8, letter 4 |
| Letting from abroad: a person in France, mail, payments, tax | Landlord | 9, letter 10 |
Question 3: do you own a holiday home that you use yourself?
An empty house is insurable, declared as a second home (résidence secondaire). Three clauses decide whether you are paid: the unoccupancy clause, which reduces or suspends a cover, usually theft, after a number of days without occupants; the prevention duties during absences, frost protection first; and the declaration of the risk (second home, occasional letting, the person who holds the keys). The reporting deadline runs from the day you, or the person looking after the house, discover the damage. If the holiday home is a flat in a co-ownership building, the co-owner’s liability insurance is compulsory even though you do not live there.
| Your question | Kit | Chapter |
|---|---|---|
| What changes for a house that stands empty, the French words of the policy | Holiday home | 1 |
| Matching the policy to your real calendar: the unoccupancy clause | Holiday home | 2, letter 3 of chapter 10 |
| Theft and vandalism while you are away | Holiday home | 3, letter 5 |
| Water damage and frost | Holiday home | 4 |
| Storm, natural disasters, forest fire and brush clearing | Holiday home | 5, letter 7 |
| Lending the house, or letting it a few weeks | Holiday home | 6, letter 4 |
| Reporting a claim from abroad, authorising a neighbour | Holiday home | 7, letters 1 and 6 |
| Reading your policy: the 20-point grid | Holiday home | 8 |
| Winterisation and the house’s year | Holiday home | 9 |
Question 4: do you hold several of these roles, or is your situation changing?
Each home has its own policy, and each change of use is declared: during the policy, any new circumstance that increases the risk or creates a new one must be declared within 15 days of learning about it (Insurance Code, art. L113-2); the insurer may then offer a new premium or cancel (art. L113-4). An undeclared change comes to light at the claim, with a reduced payout (art. L113-9) or a void policy in case of bad faith (art. L113-8). The most frequent changes:
| Your change | What it means for the insurance | Where |
|---|---|---|
| You move abroad and let your former main home year-round | The tenant now insures the home; you need a landlord policy, declared in writing | Landlord 1, 2 and 9, letter 8; Holiday home 2 |
| You start letting your holiday home a few weeks to holidaymakers | Declared in writing, with a written answer on guests, theft and recourse | Holiday home 6, letter 4; Landlord 4 |
| You let the holiday home on a lease for part of the year | During the lease, the tenant’s duty applies; in summer, the seasonal rules | Landlord 4 and 10 (case 5) |
| You rent your main home and own another home in France | Two policies, two addresses, two calendars | Tenant 2; Holiday home 2; this guide, chapter 3 |
| Your child rents a studio as a student | A policy in the child’s name, or a written confirmation from yours | Tenant 3, letter 2 |
| The home stays empty for a long time (works, for sale) | A policy that accepts long unoccupancy, often with visit conditions | Landlord 4; Holiday home 2 |
| You sell the home | The policy continues for the buyer unless cancelled; you inform the insurer by registered letter | Holiday home 10, letter 8 |
| You leave France as a tenant | Cancellation within three months of the move | Tenant 6, letter 7 |
Free guides or the pack
The free guides explain the rules. The kit gets it done: the steps in order, the deadlines and the letters.
Free guides
€0
free on this site
- ✓The rules explained, official texts cited
- —The steps in order, with the deadlines
- —8 checklist items
- —Bookmark it or print it to PDF
Home insurance pack
€49
VAT included, paid once
- ✓The rules explained, official texts cited
- ✓The steps in order, with the deadlines
- ✓8 checklist items
- ✓Bookmark it or print it to PDF
As described, or refunded · updates included, at no cost
Checkout by Stripe
Card, Apple Pay or Google Pay on Stripe’s secure page. Your card details never go through our servers.
Instant access
The complete kit opens right after payment, to bookmark or save as a PDF. Receipt and invoice by email.
VAT included, paid once
The price shown is the total. No subscription, nothing charged later.
Sources you can check
19 links to the official French texts (Légifrance, Service-public…). Not an insurer, not a broker: the kit explains the rules and sells no policy. Terms of sale.
Frequently asked questions
How do I receive the kit?
Right after payment, the confirmation page gives you the link to the complete kit, also sent by email. Bookmark the kit page or print it to PDF (Ctrl+P or Cmd+P, “Save as PDF”). Stripe also emails you the receipt.
Do I get an invoice?
Yes: Stripe generates the invoice and emails it to you.
Is the payment secure?
Yes: you pay once on our checkout page secured by Stripe, with no subscription. Your card details never go through our servers.
What is the guarantee?
The kit is guaranteed as described: if access fails or the content does not match, we restore your access or refund you (terms of sale). It is updated at no cost when the rules change. Contact: admin@tech-bharat.com.
Who publishes the kit?
Claude Assur, an independent information publisher, not an insurer, a broker or a lawyer: the kit explains the general rules and gives you the method and templates; only the official texts and your policy are authoritative.
Other kits
Complete expat pack
Insurance in France: the complete expat pack
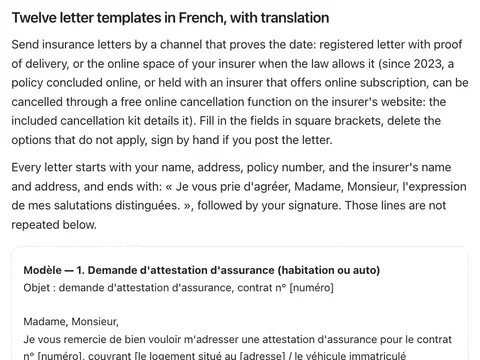
Car, home, health, claims and letting explained, 12 French letters translated, and 6 kits included.
The 6 kits alone: €90 bought separately
€89 13 chapters · instant access
See what is inside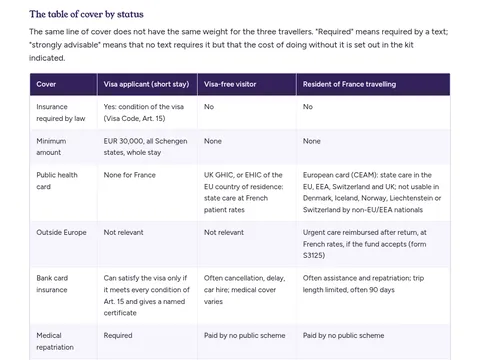
France travel pack
France travel insurance pack: visa applicant, visa-free visitor or resident
A 5-question route by traveller status, what each traveller must hold side by side, mixed households, a pre-departure calendar, and the 3 travel kits included.
The 3 kits alone: €87 bought separately
€49 6 chapters · instant access
See the pack
Car in France pack
Your car in France: the complete drivers’ pack
A 4-question route, the calendar of your first six months, every deadline in one table, 4 cases with figures, and the 3 car kits included.
The 3 kits alone: €67 bought separately
€49 6 chapters · instant access
See the pack
Founder’s pack
Business insurance in France: the founder’s pack (from freelancer to SAS or SARL)
A 4-question route from working alone to running a company, what each status must hold, the calendar to your first financial year, 4 cases with figures, and the 2 business kits included.
The 2 kits alone: €73 bought separately
€59 6 chapters · instant access
See the pack
Tenant kit
Renting in France: the tenant insurance kit
The legal duty, the right policy, students, flat-shares and furnished lets, water damage, moving out and 8 French letters translated.
€14 9 chapters · instant access
See the kit
Boat kit
Boat insurance in France: the boat owner’s kit
What the law and the marina require, agreed value, navigation zone, outboard theft, wintering, who pays after a collision, and 8 French letters translated.
€24 11 chapters · instant access
See the kit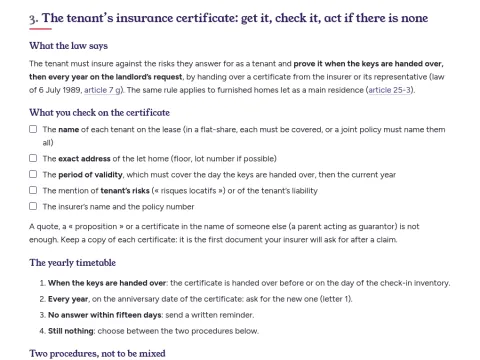
Landlord kit
Landlord insurance in France: the property owner’s kit
The landlord policy in a 12-point grid, the tenant’s certificate and what to do without it, unpaid rent (GLI, Visale), furnished lets, co-ownership rules, letting from abroad and 10 French letters translated.
€29 12 chapters · instant access
See the kit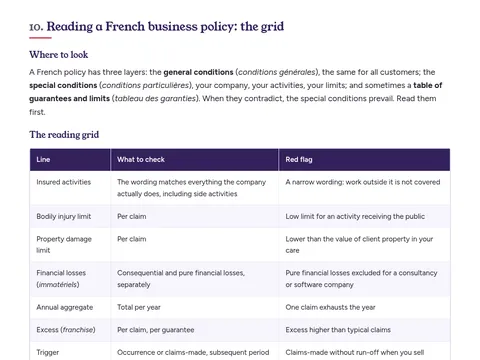
Company insurance kit
Running a company in France: the business insurance kit
What your company and staff must have, the company mutuelle, managers’ prévoyance, directors’ liability, business interruption, cyber, fleet, 6 case studies and 10 French letters translated.
€49 12 chapters · instant access
See the kit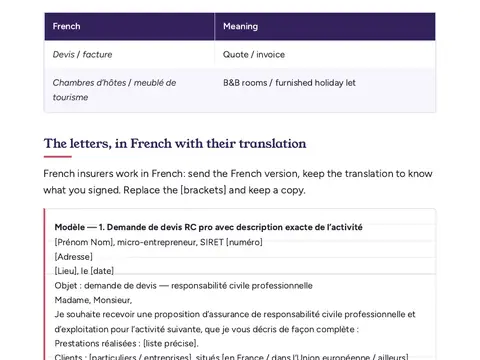
Self-employed kit
Business insurance for the self-employed in France kit
What is compulsory for your trade, the décennale, quote and invoice wording, gîtes and B&Bs, and 7 French letters translated.
€24 13 chapters · instant access
See the kit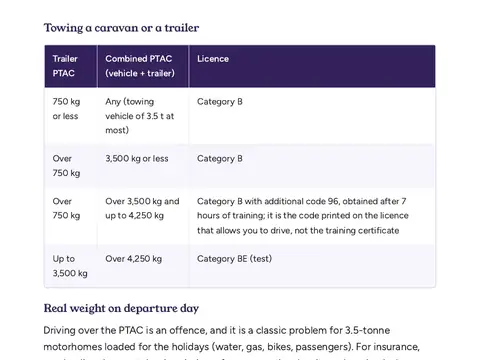
Motorhome kit
Motorhome, campervan and caravan insurance in France kit
The licence for each weight, VASP registration, a grid to read French policies, winter lay-up, renting out, claims and 8 French letters translated.
€24 10 chapters · instant access
See the kit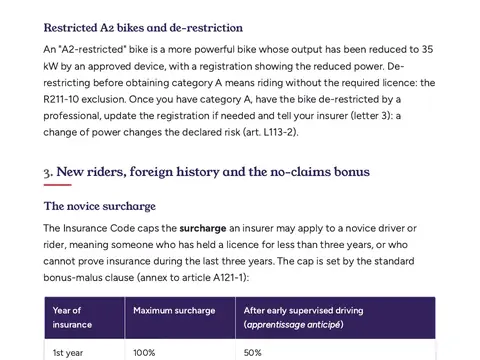
Motorbike kit
Motorbike and scooter insurance in France kit
Licence categories, your foreign history, the novice surcharge, rider cover, compulsory gloves, theft clauses, accidents and 8 French letters translated.
€19 11 chapters · instant access
See the kit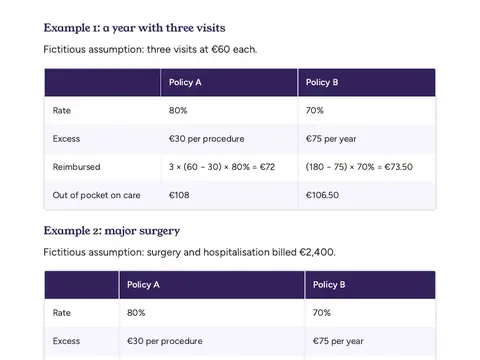
Dog and cat kit
Dog and cat insurance in France kit
The six figures of a French pet policy, a comparison grid, your out-of-pocket cost, breed exclusions, owner rules, claims and 8 French letters translated.
€19 10 chapters · instant access
See the kit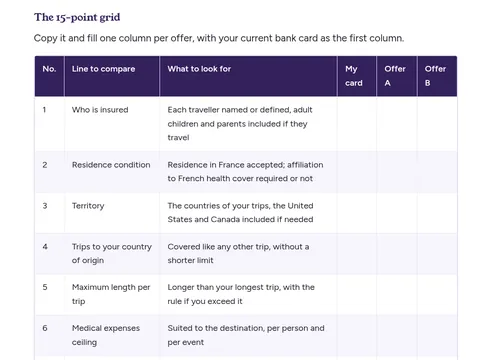
Resident travel kit
Travel insurance when you live in France: the resident’s kit
What your carte Vitale, European health card and bank card cover abroad, annual or single-trip policy, repatriation, trips home and to the US, a 15-point grid and 4 French letters translated.
€29 10 chapters · instant access
See the kit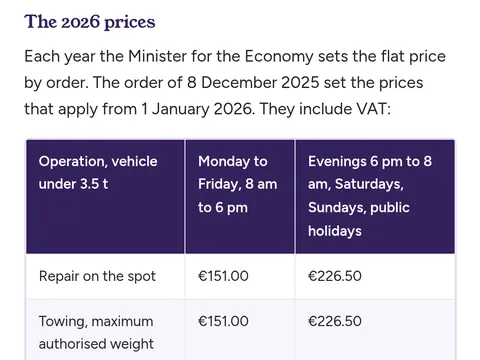
Breakdown cover kit
Breakdown cover in France: the roadside assistance kit
The 0 km clause, 2026 regulated motorway towing prices, separate contracts, foreign cars and short trips, bank cards, a 15-point grid, 4 cases with figures and 3 French letters translated.
€29 9 chapters · instant access
See the kit
Visa-free visitor kit
Visiting France without a visa: travel insurance and healthcare kit
What your GHIC, home health plan and credit card pay in France, real French hospital rates, flights, car hire, EES and ETIAS, a 15-point grid, 4 cases with figures and 4 French letters translated.
€29 10 chapters · instant access
See the kit
Schengen visa kit
Schengen visa and travel insurance for France: the compliant-policy kit
The €30,000 rule of Article 15, long-stay visas and students, bank cards and EHIC, a comparison grid, a hospital stay in France and 4 French letters translated.
€29 9 chapters · instant access
See the kit
Expat car kit
Your car in France as an expat: insure, register and drive with the right paperwork
Registration and WW plates, insurance on foreign plates, your foreign history, the right cover, the accident report box by box, cancellation and 10 French letters translated.
€29 11 chapters · instant access
See the kit
Holiday home kit
Holiday home in France: the insurance kit for owners who live elsewhere
Unoccupancy clauses, frost duties, theft, storms and natural disasters, occasional letting, claims from abroad, a 20-point policy grid and 8 French letters translated.
€29 10 chapters · instant access
See the kit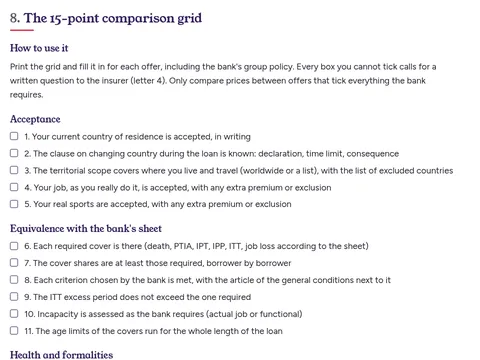
Expat mortgage insurance kit
French mortgage insurance for expats: the borrower-insurance kit
What the bank requires, bringing your own insurer before you sign, the €200,000 health rule, AERAS, your country of residence, couple shares, a 15-point grid and 6 French letters translated.
€34 9 chapters · instant access
See the kit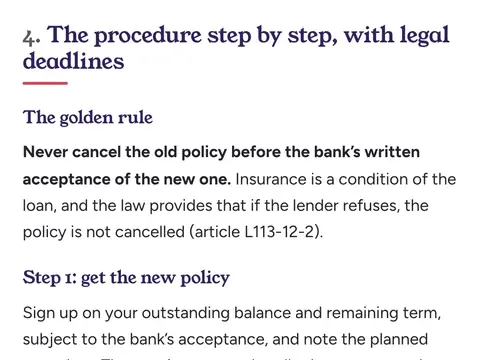
Lemoine law kit
Switching your mortgage insurance in France (Lemoine law) kit
Savings calculation, equivalent cover, step-by-step process and ready-to-send letters.
€12 8 chapters · instant access
See the kit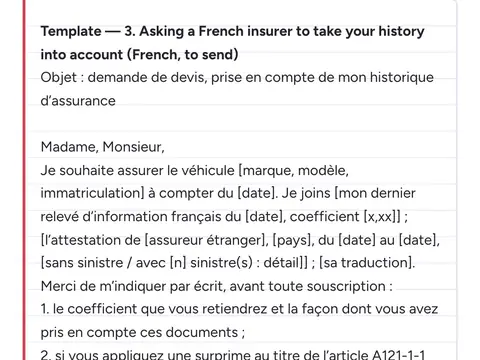
No-claims kit
French no-claims bonus and claims record kit
Work out your coefficient, get your French claims record, use your foreign no-claims, letter templates.
€9 9 chapters · instant access
See the kit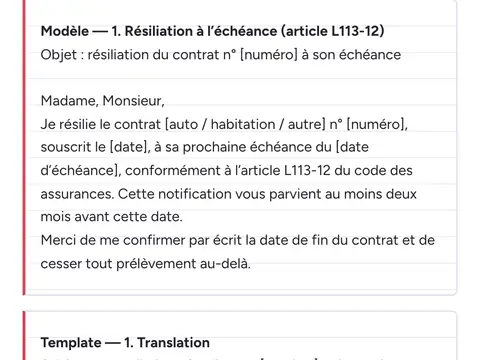
Cancellation kit
Cancelling insurance in France kit (Hamon, Chatel, health…)
Which rule applies to your policy, which notice period, and the ready-to-send letter.
€7 9 chapters · instant access
See the kitInstant access to your kit after payment · price VAT included · terms of sale. Claude Assur is not an insurer, a broker, a registered insurance intermediary (ORIAS) or a lawyer: the kits explain the general rules and are not personal advice; only the official texts and your own policy are authoritative.