Holiday home kit · updated 2026
Holiday home in France: the insurance kit for owners who live elsewhere
Who it is for: You own a house or flat in France that you use a few weeks a year and live in another country the rest of the time
- 10chapters
- 8French letters, translated
- 50checklist items
- 7tables
- 3links to the official texts
Checked before every release
- 51automated testsrun at every release: prices, links, pages and content checked before publication.
- 3links to the textsthe main official sources cited in the kit (Légifrance, Service-public…), for you to check.
- 30 October 2026last updatelatest update of this kit; you always read the latest version.
Built from the texts and data of La Médiation de l’assurance, Légifrance, Service-public.fr.
€29VAT included · one payment · instant access
Get the kit — €29 Read chapter 1 free
10 chapters online (unoccupancy clauses, frost duties, theft, storms and natural disasters, occasional letting, claims from abroad, a 20-point policy grid and 8 French letters translated). €29, VAT included, one payment, instant access, printable to PDF, invoice by email.
As described, or refunded · updates included, at no cost · terms of sale
Secure payment by Stripe · card, Apple Pay, Google Pay · Instant access, no subscription
After payment
- Instant access to the complete kit on its access page, to bookmark or print to PDF.
- Your Stripe invoice is sent to the email address you paid with.
- Your links at any time: Find my purchases emails you a link valid for 24 hours.
- A week later, one email asks for your review, only once.
- No calls, no text messages: buying does not pass your details to brokers. Only the broker request form does, with your consent.
What you get
- The complete kit: 10 chapters (unoccupancy clauses, frost duties, theft, storms and natural disasters, occasional letting, claims from abroad, a 20-point policy grid and 8 French letters translated)
- Included: 8 letter templates, 50 checklist items, 7 tables
Choose a policy that really covers a house that stands empty, protect it from theft, frost and storms, let it now and then, and handle a claim from abroad, with 8 French letters translated.
Who it is for
- You own a house or flat in France that you use a few weeks a year and live in another country the rest of the time
- You do not know how many days the house can stay empty before theft or water damage stops being covered
- You lend or let the house now and then and want to know what the insurer must be told
- You want to report a claim and get the loss adjuster in without flying over, thanks to a neighbour or caretaker you authorise
Contents of the complete kit
- What changes when nobody lives in the house (free extract below)
- Choosing the formula: unoccupancy, frost protection, length of absence
- Theft and vandalism while you are away
- Water damage and frost: the first risk of an empty house
- Storm, natural disasters and forest fire
- Lending or letting the house now and then
- Reporting a claim from abroad and authorising a neighbour
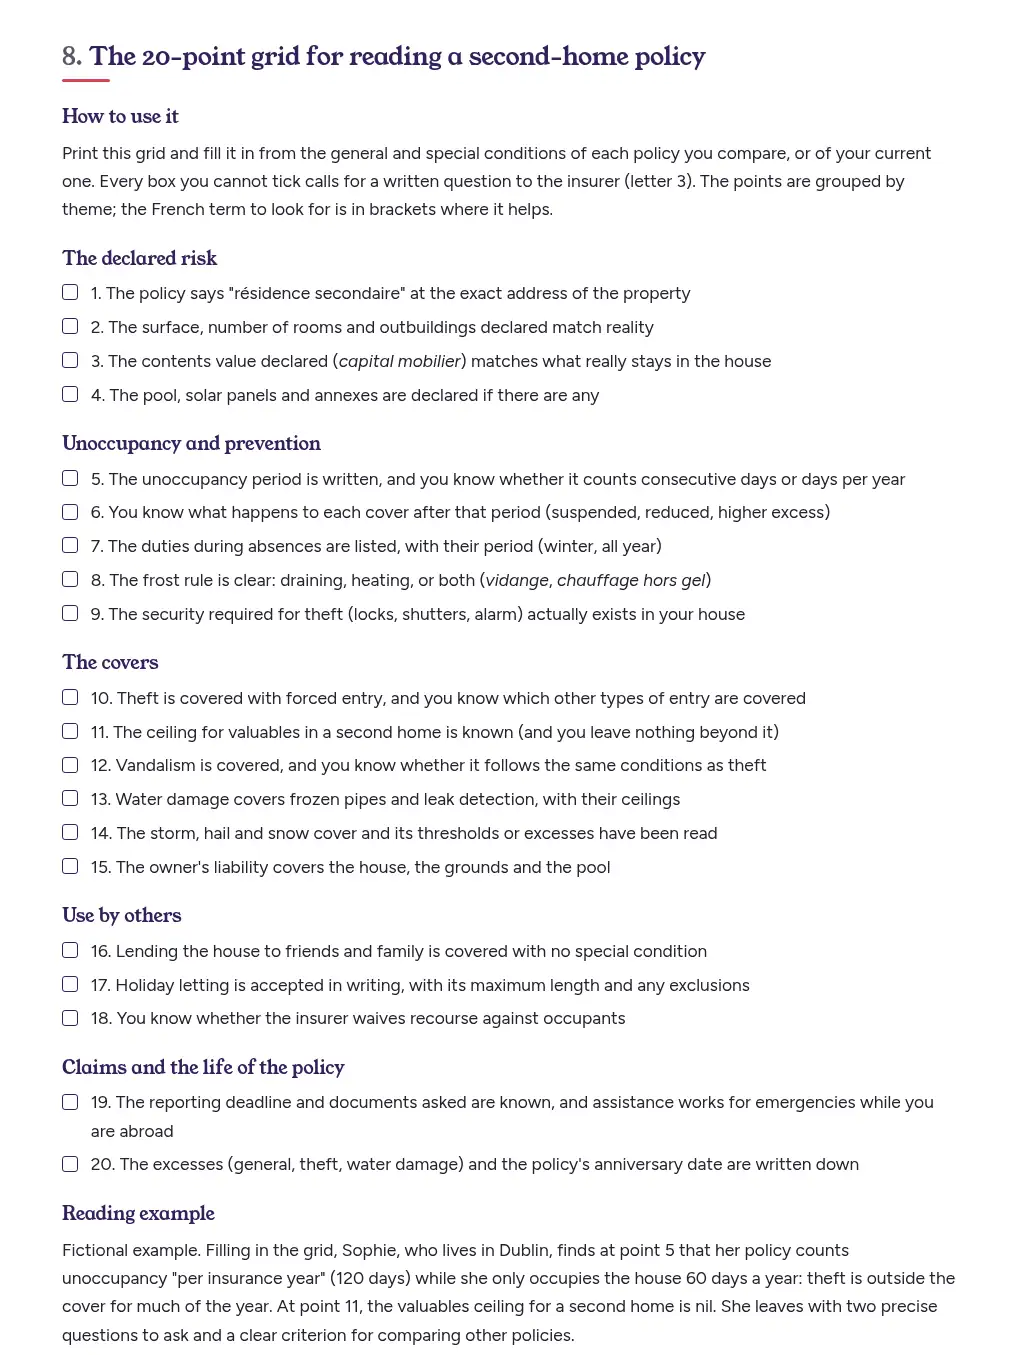
- The 20-point grid for reading a second-home policy
- The winterisation calendar and the house's year
- Eight letters in French, with their English translation
Included: 8 letter templates, 50 checklist items, 7 tables.
Introduction
A holiday home in France is insured almost like a main home, with one difference that changes everything: most of the time, nobody sleeps there. French policies know it. They cut some covers after a number of days without occupants, impose prevention duties before every departure, and expect a claim to be reported quickly, when you may only learn about it weeks later, from another country, in French. This kit teaches you to read those clauses, to choose a policy that fits the calendar you really live, and to organise the house so that, on the day of a claim, nothing can be held against you.
Chapter 1 explains what changes for a house that stands empty and gives you the French words of the policy. Chapter 2 helps you choose the formula: unoccupancy clause, frost protection, length of absence, liability. Chapters 3, 4 and 5 deal with the three risks that dominate claims on empty houses: theft and vandalism, water damage and frost, then storms, natural disasters and forest fire. Chapter 6 covers letting the house now and then. Chapter 7 shows how to report a claim from abroad and authorise someone on the spot. Chapter 8 is the 20-point grid for reading a policy, chapter 9 the winterisation calendar, chapter 10 the 8 letters in French with their English translation.
What changes when nobody lives in the house
An empty house is insurable
The idea that "an empty house cannot be insured" is wrong. It can, on precise conditions that you need to know and respect. The policy is a French home policy (multirisque habitation, MRH) declared as a second home (résidence secondaire), or a policy designed for second homes. It contains the same blocks as any MRH: fire, water damage, storm, natural disasters, theft and vandalism, broken glass, civil liability. What differs is how your absence weighs on each block.
Absence makes three things worse. The time before discovery: a leak running for three weeks does damage out of all proportion to a leak noticed within an hour. The exposure to theft: burglars quickly spot shutters that have been closed for a month. And the reporting deadline: you must report a claim "as soon as you know about it", which assumes someone notices.
Living abroad adds three more
- Distance. You cannot check the house after a storm warning, open the door to a plumber or meet the loss adjuster next Tuesday unless someone does it for you (chapter 7).
- Mail. French insurers still send formal notices by post. A formal notice for an unpaid premium produces its effects even if it sits unread in a French letterbox: cover is suspended 30 days after it, and the insurer can cancel 10 days later (article L113-3). Give the insurer an address where you really read your post, and an email address.
- Language. Contracts, claim forms and letters are in French. Chapter 1 gives you the words; chapter 10 gives you the letters, with translations so you know what you sign.
You do not need to be resident in France to insure a French home. Premiums are usually paid by SEPA direct debit, which works from most European bank accounts; ask before signing if your account is outside the euro area.
The three clauses that decide whether you are paid
- The unoccupancy clause (clause d'inoccupation or d'inhabitation). After a certain number of days without anyone living there, the policy reduces or suspends a cover, usually theft, sometimes vandalism or water damage. The number is in the general or special conditions; it varies from one policy to another and is counted either in consecutive days or in days per year.
- Prevention duties during absences: shutting off the water, draining the pipes or keeping the heating on frost setting, locking shutters and doors. They are often conditions of cover: forgetting one can reduce or cancel the payout for the related claim.
- The declaration of the risk: second home, not main home; occasional letting declared; the person who holds the keys known to the insurer. A false declaration comes to light at the claim, with the sanctions of articles L113-8 (void policy in case of bad faith) and L113-9 (reduced payout otherwise) of the Insurance Code.
The deadline runs from the day you know
Article L113-2 of the Insurance Code requires you to report a claim as soon as you know about it, and at the latest within the deadline set by the policy, which cannot be shorter than five working days, two working days for a theft. For an empty house, the words that matter are "as soon as you know": the clock starts the day you, or the person looking after the house, discover the damage, not the day of the storm. The insurer can only rely on late reporting if the policy provides for it and if it proves the delay harmed it. So always report, even late, and keep proof of the date of discovery (the neighbour's message, a dated photo).
What you can do this week
- Find your general and special conditions and mark the unoccupancy period and the prevention duties
- Check that the policy says "résidence secondaire" at the right address
- Write the claims phone number and policy number on a card and give it to the person who holds the keys
- Photograph each room and every valuable item, and store the photos outside the house
- Note where the main water valve, the fuse box and the gas valve are
- Check which postal and email address the insurer has for you
The French words of the policy
| French | What it means for you |
|---|---|
| résidence secondaire | Second home, used part of the year |
| multirisque habitation (MRH) | The standard French home policy |
| clause d'inoccupation, d'inhabitation | Length of absence after which a cover is reduced or suspended |
| mise hors gel | Heating set to prevent frozen pipes, or draining the system |
| mesures de prévention | Duties imposed by the policy during absences |
| effraction | Forced entry; most theft covers require it |
| franchise | The excess, the part of the loss you pay yourself |
| franchise légale | The excess set by law for natural disasters, which no policy can waive |
| arrêté de catastrophe naturelle | The decree published in the Official Journal that opens the natural-disaster cover |
| renonciation à recours, abandon de recours | Your insurer waives its right to claim against an occupant (guest, tenant) |
| propriétaire non occupant (PNO) | Landlord policy, for a home let year-round |
| mandat, mandataire | Written authority given to someone to act for you; the person who receives it |
| expert, contre-expertise | The loss adjuster who values the claim for the insurer; an adjuster you appoint to challenge it |
| déclaration de sinistre | Reporting a claim |
| échéance, résiliation | The policy's anniversary date, cancellation |
| conditions générales, conditions particulières | The standard terms, and your own policy schedule |
Free guides or the kit
The free guides explain the rules. The kit gets it done: the steps in order, the deadlines and the letters.
Free guides
€0
free on this site
- ✓The rules explained, official texts cited
- —The steps in order, with the deadlines
- —8 French letters with their translation
- —50 checklist items
- —Bookmark it or print it to PDF
Holiday home kit
€29
VAT included, paid once
- ✓The rules explained, official texts cited
- ✓The steps in order, with the deadlines
- ✓8 French letters with their translation
- ✓50 checklist items
- ✓Bookmark it or print it to PDF
As described, or refunded · updates included, at no cost
Checkout by Stripe
Card, Apple Pay or Google Pay on Stripe’s secure page. Your card details never go through our servers.
Instant access
The complete kit opens right after payment, to bookmark or save as a PDF. Receipt and invoice by email.
VAT included, paid once
The price shown is the total. No subscription, nothing charged later.
Sources you can check
3 links to the official French texts (Légifrance, Service-public…). Not an insurer, not a broker: the kit explains the rules and sells no policy. Terms of sale.
Frequently asked questions
How do I receive the kit?
Right after payment, the confirmation page gives you the link to the complete kit, also sent by email. Bookmark the kit page or print it to PDF (Ctrl+P or Cmd+P, “Save as PDF”). Stripe also emails you the receipt.
Do I get an invoice?
Yes: Stripe generates the invoice and emails it to you.
Is the payment secure?
Yes: you pay once on our checkout page secured by Stripe, with no subscription. Your card details never go through our servers.
What is the guarantee?
The kit is guaranteed as described: if access fails or the content does not match, we restore your access or refund you (terms of sale). It is updated at no cost when the rules change. Contact: admin@tech-bharat.com.
Who publishes the kit?
Claude Assur, an independent information publisher, not an insurer, a broker or a lawyer: the kit explains the general rules and gives you the method and templates; only the official texts and your policy are authoritative.
Other kits
Complete expat pack
Insurance in France: the complete expat pack
Car, home, health, claims and letting explained, 12 French letters translated, and 6 kits included.
The 6 kits alone: €90 bought separately
€89 13 chapters · instant access
See what is inside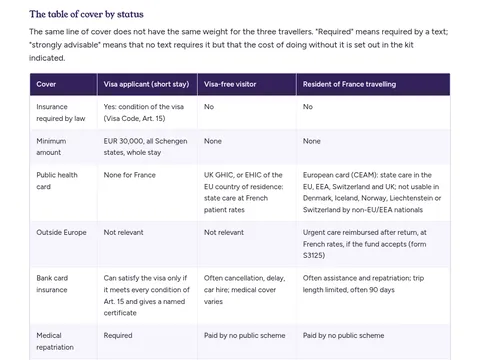
France travel pack
France travel insurance pack: visa applicant, visa-free visitor or resident
A 5-question route by traveller status, what each traveller must hold side by side, mixed households, a pre-departure calendar, and the 3 travel kits included.
The 3 kits alone: €87 bought separately
€49 6 chapters · instant access
See the pack
Car in France pack
Your car in France: the complete drivers’ pack
A 4-question route, the calendar of your first six months, every deadline in one table, 4 cases with figures, and the 3 car kits included.
The 3 kits alone: €67 bought separately
€49 6 chapters · instant access
See the pack
Founder’s pack
Business insurance in France: the founder’s pack (from freelancer to SAS or SARL)
A 4-question route from working alone to running a company, what each status must hold, the calendar to your first financial year, 4 cases with figures, and the 2 business kits included.
The 2 kits alone: €73 bought separately
€59 6 chapters · instant access
See the pack
Home insurance pack
Home insurance in France: the tenant, landlord and holiday-home pack (one route, three kits)
A 4-question route by role, who must insure what side by side, 4 households with several homes, one calendar for all your homes, and the 3 home kits included.
The 3 kits alone: €72 bought separately
€49 6 chapters · instant access
See the pack
Tenant kit
Renting in France: the tenant insurance kit
The legal duty, the right policy, students, flat-shares and furnished lets, water damage, moving out and 8 French letters translated.
€14 9 chapters · instant access
See the kit
Boat kit
Boat insurance in France: the boat owner’s kit
What the law and the marina require, agreed value, navigation zone, outboard theft, wintering, who pays after a collision, and 8 French letters translated.
€24 11 chapters · instant access
See the kit
Landlord kit
Landlord insurance in France: the property owner’s kit
The landlord policy in a 12-point grid, the tenant’s certificate and what to do without it, unpaid rent (GLI, Visale), furnished lets, co-ownership rules, letting from abroad and 10 French letters translated.
€29 12 chapters · instant access
See the kit
Company insurance kit
Running a company in France: the business insurance kit
What your company and staff must have, the company mutuelle, managers’ prévoyance, directors’ liability, business interruption, cyber, fleet, 6 case studies and 10 French letters translated.
€49 12 chapters · instant access
See the kit
Self-employed kit
Business insurance for the self-employed in France kit
What is compulsory for your trade, the décennale, quote and invoice wording, gîtes and B&Bs, and 7 French letters translated.
€24 13 chapters · instant access
See the kit
Motorhome kit
Motorhome, campervan and caravan insurance in France kit
The licence for each weight, VASP registration, a grid to read French policies, winter lay-up, renting out, claims and 8 French letters translated.
€24 10 chapters · instant access
See the kit
Motorbike kit
Motorbike and scooter insurance in France kit
Licence categories, your foreign history, the novice surcharge, rider cover, compulsory gloves, theft clauses, accidents and 8 French letters translated.
€19 11 chapters · instant access
See the kit
Dog and cat kit
Dog and cat insurance in France kit
The six figures of a French pet policy, a comparison grid, your out-of-pocket cost, breed exclusions, owner rules, claims and 8 French letters translated.
€19 10 chapters · instant access
See the kit
Resident travel kit
Travel insurance when you live in France: the resident’s kit
What your carte Vitale, European health card and bank card cover abroad, annual or single-trip policy, repatriation, trips home and to the US, a 15-point grid and 4 French letters translated.
€29 10 chapters · instant access
See the kit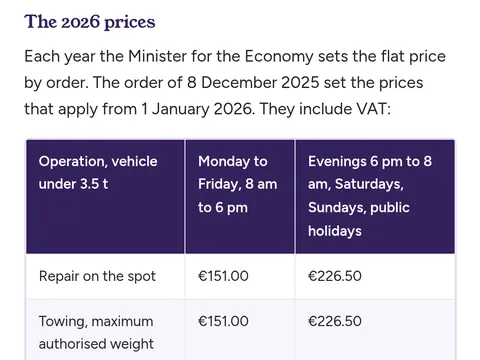
Breakdown cover kit
Breakdown cover in France: the roadside assistance kit
The 0 km clause, 2026 regulated motorway towing prices, separate contracts, foreign cars and short trips, bank cards, a 15-point grid, 4 cases with figures and 3 French letters translated.
€29 9 chapters · instant access
See the kit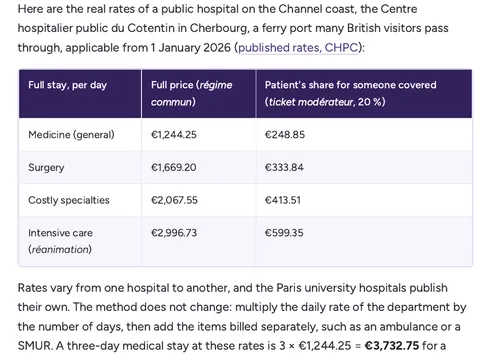
Visa-free visitor kit
Visiting France without a visa: travel insurance and healthcare kit
What your GHIC, home health plan and credit card pay in France, real French hospital rates, flights, car hire, EES and ETIAS, a 15-point grid, 4 cases with figures and 4 French letters translated.
€29 10 chapters · instant access
See the kit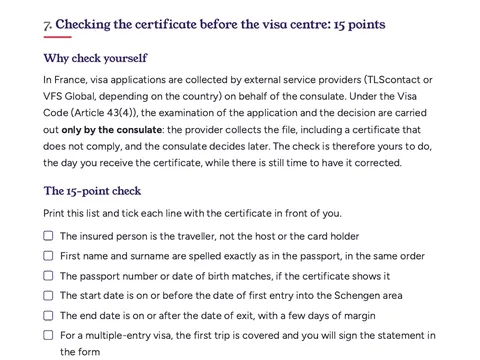
Schengen visa kit
Schengen visa and travel insurance for France: the compliant-policy kit
The €30,000 rule of Article 15, long-stay visas and students, bank cards and EHIC, a comparison grid, a hospital stay in France and 4 French letters translated.
€29 9 chapters · instant access
See the kit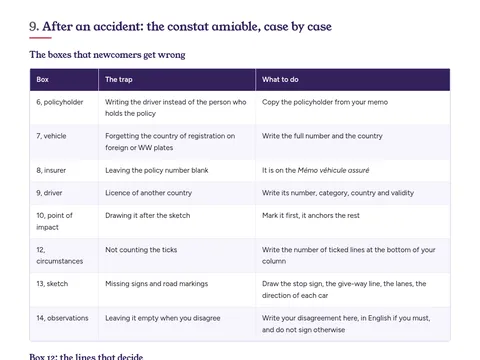
Expat car kit
Your car in France as an expat: insure, register and drive with the right paperwork
Registration and WW plates, insurance on foreign plates, your foreign history, the right cover, the accident report box by box, cancellation and 10 French letters translated.
€29 11 chapters · instant access
See the kit
Expat mortgage insurance kit
French mortgage insurance for expats: the borrower-insurance kit
What the bank requires, bringing your own insurer before you sign, the €200,000 health rule, AERAS, your country of residence, couple shares, a 15-point grid and 6 French letters translated.
€34 9 chapters · instant access
See the kit
Lemoine law kit
Switching your mortgage insurance in France (Lemoine law) kit
Savings calculation, equivalent cover, step-by-step process and ready-to-send letters.
€12 8 chapters · instant access
See the kit
No-claims kit
French no-claims bonus and claims record kit
Work out your coefficient, get your French claims record, use your foreign no-claims, letter templates.
€9 9 chapters · instant access
See the kit
Cancellation kit
Cancelling insurance in France kit (Hamon, Chatel, health…)
Which rule applies to your policy, which notice period, and the ready-to-send letter.
€7 9 chapters · instant access
See the kitInstant access to your kit after payment · price VAT included · terms of sale. Claude Assur is not an insurer, a broker, a registered insurance intermediary (ORIAS) or a lawyer: the kits explain the general rules and are not personal advice; only the official texts and your own policy are authoritative.